Research Insight Hub is a global research and business-intelligence resource created to help companies discover meaningful market opportunities, understand industry change, and support better commercial decisions. We offer syndicated market reports, customized research engagements, consulting support, and analytical insights across a diverse range of markets and business sectors. Research Insight Hub helps decision-makers navigate complex questions related to market potential, emerging trends, customer demand, competitive activity, investment priorities, and future industry direction. Our research is developed for organizations that require reliable market context before launching products, entering new regions, expanding operations, assessing partnerships, or refining their strategic priorities.
Our approach integrates qualitative insight with quantitative analysis. We review relevant industry sources, corporate developments, government and trade information, technical publications, market indicators, and available expert perspectives to build a well-rounded view of each market. By examining market drivers, restraints, opportunities, challenges, segmentation, and regional performance, we aim to provide analysis that is both comprehensive and easy to use. Research Insight Hub covers industries such as healthcare and life sciences, technology, consumer markets, food and beverage, energy, industrial products, chemicals and materials, automotive, retail, financial services, media, logistics, and sustainability-focused markets. We recognize that each client has different information needs, so our research solutions can be adapted to specific geographies, customer groups, product categories, competitors, and strategic objectives. At Research Insight Hub, our purpose is to make research more practical. We transform market information into focused insights that help professionals recognize what is changing, why it matters, and how they can respond. Through timely analysis and client-oriented research support, Research Insight Hub strives to be a dependable partner for informed business growth.
Predictive AI In Stock Market Outlook: CAGR 17.3% to 2033
Predictive AI In Stock Market by Predictive Ai In Stock Market Is Segmented By Component (Solution, Services), by Application (Algorithmic trading, Portfolio management, Risk management, Sentiment analysis, Others), by End-User (Institutional investors, Retail investors, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Base Year: 2025
274 Pages
Srinwanti Kar
Senior Research Analyst
Predictive AI In Stock Market Outlook: CAGR 17.3% to 2033
Yoga Mat Market is projected to reach $23.8B by 2033, growing at 4.51% CAGR. Explore drivers, segment shifts, and regional dynamics shaping the industry.
Applied AI In Retail And E Commerce Market expands from USD 3.6 billion in 2024 at a 54.7% CAGR, reaching USD 182.6 billion by 2033 on cloud AI adoption.
The Workforce Analytics Market Industry Share Analysis grows at 14.3% CAGR driven by AI talent insights. Access our 2034 forecast for strategic planning.
AI Task Manager App Market grows at 10.4% CAGR as AI automation reshapes productivity. See our 2025-2033 forecast, vendor rankings, and regional data.
September 2026Base Year: 2025No Of Pages: 274
Price: $4480
Market at a glance
Metric
Value
Base Year Valuation (2025)
USD 295.7 million
Forecast Valuation (2033)
USD 1,059.8 million
CAGR (2025-2033)
17.3%
Forecast Period
2025-2033
Largest Regional Market
North America (42.0% of global revenue)
Dominant Segment
Solutions software (68% of component revenue)
Key Insights & Executive Summary: Predictive AI In Stock Market
The Predictive AI In Stock Market is sized at USD 295.7 million in 2025 and is forecast to reach USD 1,059.8 million by 2033, equal to a 17.3% CAGR and a 3.6x expansion across eight years. Unlike earlier quantitative tooling cycles, revenue is being captured by software rather than by discretionary advisory services: solutions account for roughly 68% of component revenue and services for 32%.
Predictive AI In Stock Market Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
296.0 M
2025
347.0 M
2026
407.0 M
2027
477.0 M
2028
560.0 M
2029
657.0 M
2030
770.0 M
2031
Three structural forces set the pace:
Compute deflation. GPU capacity and inference-optimized silicon cut the cost of training and serving a production forecasting model by an estimated 35-45% between 2022 and 2025.
Input breadth. The Alternative Data Market, spanning card-panel transactions, satellite imagery and shipping telemetry, now supplies production features rather than pilot datasets, widening the signal base for equity and macro models.
Fee compression. Active managers operating on 50-70 basis point blended fees rely on model-driven selection to defend net returns against passive alternatives.
Sitting inside the wider Artificial Intelligence Market, stock prediction is a narrow but high-margin vertical because outputs are directly monetizable and buyers already hold mature data infrastructure. Capability spillover from the broad Machine Learning Market - transformer architectures, retrieval-augmented pipelines, automated feature stores - shortened vendor build cycles to 9-15 months for a first commercial product.
Application mix is uneven. Algorithmic trading is the single largest application at about 41% of 2025 application revenue, followed by portfolio construction and risk overlays. The Portfolio Management Market for model-assisted allocation is the fastest-converting category among mid-size asset managers because rebalancing decisions are repeatable and measurable against a benchmark.
End-user concentration is high. Institutional desks - hedge funds, systematic asset managers and proprietary trading groups - represent roughly 63% of spend, while the Retail Investors Market accounts for most of the remainder through broker-embedded signal tools and screeners.
The principal risks are not technical. Model decay during regime shifts, explainability obligations under emerging AI audit rules, and rising costs of licensed market data could compress gross margins by 300-500 basis points for vendors that cannot reprice contracts annually.
Segment Deep-Dive: Solution Layer Dominance in Predictive AI In Stock Market
Segment
CAGR (2025-2033)
2025 Revenue Share
Key Demand Driver
Solutions (platforms, model infrastructure)
18.1%
68%
Low-latency inference and backtest infrastructure
Services (integration, MLOps, tuning)
14.2%
32%
Model governance, audit trails, compliance documentation
Algorithmic trading (application)
19.4%
41%
Execution alpha and transaction cost analysis
Institutional investors (end-user)
16.8%
63%
Fiduciary mandates and risk-adjusted return targets
Predictive AI In Stock Market Company Market Share
Loading chart...
Solutions Software: The Revenue Core
Solutions hold the largest revenue pool at 68% of 2025 component revenue, equivalent to approximately USD 201 million. Sub-dynamics:
Feature stores and data pipelines are the highest-attach sub-layer; about 7 in 10 enterprise deployments purchase them within the first contract year.
Model serving is the fastest-growing sub-layer at an estimated 21% CAGR, as firms move from nightly batch scoring to intraday inference.
Backtesting engines are commoditizing, with license pricing down 20-30% since 2022 as open-source frameworks absorb basic functionality.
Margin structure favors pure software: gross margins sit at 72-80% for platform vendors versus 45-55% for integration-heavy services. That gap explains the migration toward consumption-based pricing tied to predictions served rather than seat licenses, since it aligns vendor revenue with buyer usage intensity.
Application Layer: Algorithmic Trading Leads
The Algorithmic Trading Market is the largest application pool, at roughly 41% of application revenue, driven by execution algorithms that blend short-horizon price forecasts with venue-selection logic. Two adjacent pools behave differently:
The Sentiment Analysis Market is smaller but converts faster, since news, transcript and social feeds require lighter infrastructure than a full trading stack.
The Risk Management Market is the most defensible, because regulatory reporting and stress-testing budgets are far less cyclical than alpha budgets.
Buyers increasingly bundle all three rather than procuring in isolation, which structurally favors vendors operating a single multi-application architecture over point-solution specialists.
End-User Concentration and Margin Pressure
The Institutional Investors Market supplies about 63% of spend, concentrated in an estimated 1,200-1,500 systematic funds worldwide. Retail distribution is expanding through broker-embedded tools, but average contract values run 8-12x lower and churn is materially higher.
Pressures to monitor:
Data licensing inflation: exchange and vendor feed fees rise 5-9% annually, hitting resellers hardest.
Model decay: factor crowding shortens the useful life of proprietary signals, forcing quarterly retraining cycles.
Primary Market Drivers & Growth Restraints in Predictive AI In Stock Market
Factor Type
Description
Impact Level
Timeline
Driver
Compute cost deflation of 35-45% since 2022 reduces cost per prediction
High
Short term
Driver
Expansion of alternative data supply raises model input breadth
High
Short term
Driver
Fee compression pushes active managers toward systematic selection
High
Long term
Driver
Broker and retail API access widens the addressable buyer base
Medium
Long term
Restraint
Model decay and factor crowding shorten signal half-life
High
Short term
Restraint
Market data licensing fees rising 5-9% annually
Medium
Long term
Restraint
Explainability and AI audit requirements raise compliance cost
Medium
Long term
Restraint
Saturated alpha space limits incremental gains from basic models
Medium
Long term
Compute deflation is the strongest near-term catalyst. Training plus inference cost for a mid-complexity equity forecasting model fell from an estimated USD 180,000 in 2021 to under USD 95,000 in 2025 at equivalent accuracy, widening vendor gross margins and lowering the proof-of-concept threshold for buyers.
Data breadth compounds with compute. Firms ingesting four or more alternative datasets report hit rates 6-11 percentage points above single-source models, a measurable gap that sustains premium pricing and justifies multi-year data contracts.
Regulatory clarity is emerging rather than receding. Framework-based supervision from the U.S. Securities and Exchange Commission and the EU AI Act high-risk classification create compliance overhead, but they also raise switching costs for incumbents that already document model lineage and validation history.
On the restraint side:
Model decay is structural. The average live performance of published cross-sectional signals decays roughly 50% within 18-24 months of publication.
Data cost inflation runs 5-9% annually, outpacing compute deflation and squeezing thin-margin resellers first.
Validation cost for supervised deployment - independent verification, backtest audits, out-of-sample documentation - adds 10-18% to total implementation spend.
Net effect: the market grows steadily but vendor economics diverge. Platforms holding proprietary data and charging on consumption capture disproportionate margin, while seat-licensed analytics vendors face flat pricing power.
Competitive Ecosystem & Key Vendor Profiles: Predictive AI In Stock Market
Company Name
Core Strength
Target Audience
Market Position
NVIDIA Corp.
GPU and inference infrastructure
Platform vendors, quant funds
Leader
Microsoft Corp.
Azure AI services and exchange partnerships
Institutional asset managers
Leader
Amazon Web Services Inc.
Managed model hosting and vector services
Buy-side and sell-side IT teams
Leader
Alphabet Inc.
Foundation models and Vertex AI distribution
Enterprise quant teams
Leader
International Business Machines Corp.
Governance and model-risk tooling
Regulated financial institutions
Challenger
Palantir Technologies Inc.
Deployment frameworks tying market, position and risk data
Asset managers, exchanges
Challenger
C3.ai Inc.
Packaged enterprise predictive applications
Financial services and industrials
Challenger
SAS Institute Inc.
Statistical modelling and validation analytics
Banks, insurers, regulators
Leader
DataRobot Inc.
Automated machine learning
Mid-market analytics teams
Challenger
Trade Ideas LLC
Retail-facing AI signal generation
Retail traders
Niche
QuantConnect Corp.
Open cloud backtesting and live trading
Quant developers
Niche
TrendSpider LLC
Automated technical charting and scanning
Retail and semi-pro traders
Niche
NVIDIA Corp.: Supplies the compute substrate for training and inference; its data-center roadmap effectively sets the cost curve every forecasting vendor prices against.
Microsoft Corp.: Bundles Azure AI with a long-term data and analytics partnership with London Stock Exchange Group, positioning itself as default infrastructure for institutional buy-side workflows.
Amazon Web Services Inc.: Managed hosting and vector services lower the entry cost for mid-size funds that lack internal MLOps teams.
Alphabet Inc.: Competes through model quality and cloud distribution rather than financial-domain specialization.
International Business Machines Corp.: Focuses on governance, model inventory and auditability, which matters under the EU AI Act and SEC examination regimes.
Palantir Technologies Inc.: Deploys ontology-based pipelines connecting market, position and risk data inside one operational layer.
C3.ai Inc.: Sells packaged predictive applications across industries, with financial services as a named target vertical.
SAS Institute Inc.: Retains strength in regulated risk analytics and model validation, where documentation rigor outweighs raw prediction speed.
DataRobot Inc.: Automation-first positioning suits firms without dedicated data science teams.
Trade Ideas LLC and TrendSpider LLC: Serve the retail segment with signal generation and visualization, where contract values are low but user volumes are high.
Strategic Milestones & Recent Developments in Predictive AI In Stock Market
Date
Company
Event Type
Impact
Dec 2022
Microsoft Corp.
Partnership
10-year data and AI partnership with London Stock Exchange Group including an approximate USD 2 billion investment; anchors Azure in buy-side workflows
Apr 2023
Palantir Technologies Inc.
Launch
AIP brought large-language-model workflows into operational financial data environments
May 2023
International Business Machines Corp.
Launch
watsonx packaged governance and model lifecycle tooling for regulated industries
Feb 2024
Salesforce Inc.
Launch
Einstein Copilot extended generative assistants into financial services workflows
Mar 2024
NVIDIA Corp.
Launch
Blackwell architecture raised training and inference throughput per rack
2024-2025
Alphabet Inc.
Launch
Gemini model family integrated into Google Cloud Vertex AI for enterprise deployment
Detailed chronology:
December 2022 - Microsoft Corp. and London Stock Exchange Group. A 10-year strategic partnership with roughly USD 2 billion of investment shifted a large share of the exchange group's data platform onto Azure, normalizing cloud delivery of market data at institutional scale.
April 2023 - Palantir Technologies Inc. released AIP. The platform let analysts run model-assisted workflows directly against operational financial datasets, accelerating deployment timelines from quarters to weeks for target clients.
May 2023 - International Business Machines Corp. launched watsonx. Governance, lineage and lifecycle features addressed the audit requirements that had stalled earlier model deployments inside regulated institutions.
February 2024 - Salesforce Inc. introduced Einstein Copilot for financial services. The move pushed generative assistants into client-facing advisory and servicing tasks adjacent to prediction workflows.
March 2024 - NVIDIA Corp. introduced Blackwell. Higher throughput per rack lowered the effective cost of large training runs and widened the feasible model-size range for mid-tier buyers.
2024-2025 - Alphabet Inc. integrated the Gemini family into Vertex AI. Enterprise availability made foundation models accessible without dedicated infrastructure ownership.
Regional Market Analysis & Growth Corridors for Predictive AI In Stock Market
Region
Projected CAGR (%)
Base Year Valuation (USD mn)
Primary Catalyst
Regulatory Stringency
North America
16.4%
124.2
Deep systematic fund base and mature alternative data supply
High
Europe
18.9%
71.0
Execution analytics demand and EU AI Act compliance tooling
High
Asia-Pacific
19.8%
76.9
Retail brokerage growth and exchange API liberalization
Medium-High
South America
15.1%
11.8
Early institutional adoption with few local data vendors
Medium
Middle East & Africa
14.6%
11.8
Sovereign fund modernization programs
Medium-Low
North America remains the most mature and largest pool at USD 124.2 million in 2025, or 42.0% of global revenue. Its growth rate, 16.4%, trails the global average because penetration among large systematic funds already exceeds an estimated 55%. Defensibility here rests on data access and existing compliance infrastructure rather than on new buyer acquisition.
Asia-Pacific is the fastest-growing corridor at 19.8% CAGR, supported by a rapidly expanding retail brokerage base and gradual liberalization of exchange connectivity. China, Japan, India, South Korea and ASEAN markets each contribute distinct demand profiles, with India showing the steepest retail conversion.
Europe grows at 18.9%, with MiFID-driven best-execution evidence requirements creating a durable, non-discretionary budget line for execution analytics. The EU AI Act classification of financial scoring models raises compliance cost, but it also entrenches vendors that already maintain model documentation.
LAMEA combines the smallest pools with the widest dispersion. South America and the Middle East & Africa each sit near USD 11.8 million, and both depend on sovereign wealth fund modernization and a limited number of local data vendors, keeping near-term growth below the global average.
Investment, M&A & Funding Activity in Predictive AI In Stock Market
Period
Activity Type
Representative Example
Strategic Rationale
2022-2023
Strategic investment
Microsoft Corp. and London Stock Exchange Group
Secure cloud distribution of market data and analytics
2023-2024
Platform expansion
Palantir AIP and IBM watsonx
Capture governance-led enterprise budgets
2024-2025
Venture funding
Alternative data and MLOps startups
Feed the model input and deployment pipeline
2024-2025
Bolt-on acquisition
Analytics vendors absorbed into larger software groups
Add financial-domain models to broader platforms
Capital formation in this market is weighted toward infrastructure and input supply rather than toward end-user signal products. Three patterns define the last three years:
Strategic over financial investment. Hyperscalers invest to secure distribution and workload volume, not minority economics.
Data asset acquisition. Acquirers target aggregators holding exclusive or semi-exclusive feeds, because feed exclusivity is the hardest moat to replicate.
Early-stage concentration. Seed and Series A funding clusters in alternative data ingestion and model observability, the two sub-segments where build cost is high and buyer willingness to pay is proven.
Sustainability, ESG & Decarbonization Pressures on Predictive AI In Stock Market
Pressure Vector
Mechanism
Effect on Vendors and Buyers
Inference energy intensity
Model serving clusters drawing megawatt-scale continuous load
Procurement shifting toward lower-PUE cloud regions and renewable power agreements
Scope 2 disclosure
Cloud emissions now reported in vendor ESG statements
Buyers weighting cloud-region carbon intensity during vendor selection
Circular procurement clauses appearing in multi-year enterprise contracts
Climate-risk data demand
Investors require transition and physical risk factors
New modelling modules layered onto existing prediction platforms
The environmental footprint of prediction is dominated by inference, not by training. Continuous intraday scoring across thousands of instruments produces a persistent load profile that is harder to shift to off-peak windows than batch training jobs, so carbon intensity per prediction becomes a procurement criterion rather than a marketing claim.
Secondary pressures are commercial rather than regulatory. Buyers increasingly request cloud-region carbon reporting alongside model accuracy benchmarks, and a small but growing number of institutional mandates now screen vendors on disclosed Scope 2 intensity. Hardware turnover adds a second axis: accelerator refresh intervals of roughly 18-24 months create disposal obligations that larger buyers are pushing upstream through contract terms.
methodology
Primary Research
Primary research accounts for 70-80% of total project input, with the remaining 20-30% drawn from secondary and syndicated sources. Interviews were conducted with decision-makers across the full predictive AI value chain for equity and multi-asset trading.
Company types interviewed in this market's exact value chain:
Predictive AI and quantitative signal platform vendors selling forecasting, ranking and execution models.
Alternative data aggregators supplying card-panel transactions, satellite imagery, web-scraped pricing and shipping telemetry feeds.
Cloud and accelerated-compute providers hosting financial inference workloads under low-latency interconnect.
Broker-dealers, execution venues and smart-order-router operators with embedded algorithmic routing.
Buy-side systematic asset managers, quant hedge funds and model-validation consultancies.
Stakeholder job titles interviewed: Chief Investment Officer (systematic and multi-strategy funds); Head of Quantitative Research; Algorithmic Trading Desk Director; Machine Learning Engineering Lead; Model Risk and Compliance Officer.
Industry associations and regulatory bodies referenced for governance context: U.S. Securities and Exchange Commission (SEC), Financial Industry Regulatory Authority (FINRA), European Securities and Markets Authority (ESMA), International Organization of Securities Commissions (IOSCO), and the CFA Institute.
Quantitative metrics used in bottom-up sizing: number of systematic and quant-driven funds globally; average annual spend on prediction and analytics tooling per fund; share of global equities turnover executed algorithmically; average number of production ML models maintained per buy-side firm.
Secondary Research & Industry Benchmarking
Secondary research (20-30% of input) draws on financial and transaction databases including Bloomberg, Factiva, Hoovers and PitchBook, used for vendor revenue triangulation, funding rounds and ownership structures.
Exchange filings, broker technology disclosures and cloud provider case documentation are benchmarked against interview responses to identify divergence and confirm or revise segment-level estimates.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously. Top-down modelling starts from total global financial services IT and analytics spend and isolates the share allocated to prediction, signal generation and execution analytics.
Bottom-up modelling multiplies verified buyer counts by average annual contract value, segmented by institutional, retail and exchange-side demand pools, then applies attach rates for solutions versus services.
Inputs are validated through multi-level data triangulation across three independent layers: vendor-side revenue disclosure, buy-side budget interviews, and infrastructure consumption proxies such as inference volume and data-feed licensing.
Segment splits (Component, Application, End-User) and all regional values are reconciled so that bottoms-up sums equal top-down totals within a tolerance band of plus or minus 3%.
Data Accuracy & Quality Check
Every report carries a guaranteed estimated data accuracy level of 85-90%, with confidence intervals disclosed for segment-level figures.
Quality control includes duplicate respondent screening, cross-validation of quantitative answers against filed financials, and outlier review by a second senior analyst before publication.
All datasets, forecasts and vendor profiles are refreshed and updated to the date of purchase, so the delivered file reflects the latest available regulatory filings, funding events and product announcements.
Where primary and secondary sources diverge by more than 8%, the primary interview data is retained and the discrepancy is footnoted in the delivered workbook.
Predictive AI In Stock Market Segmentation
1. Predictive Ai In Stock Market Is Segmented By Component
1.1. Solution
1.2. Services
2. Application
2.1. Algorithmic trading
2.2. Portfolio management
2.3. Risk management
2.4. Sentiment analysis
2.5. Others
3. End-User
3.1. Institutional investors
3.2. Retail investors
3.3. Others
Predictive AI In Stock Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Predictive AI In Stock Market Regional Market Share
Loading chart...
Predictive AI In Stock Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Predictive AI In Stock Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 17.3% from 2020-2034
Segmentation
By Predictive Ai In Stock Market Is Segmented By Component
Solution
Services
By Application
Algorithmic trading
Portfolio management
Risk management
Sentiment analysis
Others
By End-User
Institutional investors
Retail investors
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. RIH Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
5.1.1. Solution
5.1.2. Services
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Algorithmic trading
5.2.2. Portfolio management
5.2.3. Risk management
5.2.4. Sentiment analysis
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. Institutional investors
5.3.2. Retail investors
5.3.3. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
6.1.1. Solution
6.1.2. Services
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Algorithmic trading
6.2.2. Portfolio management
6.2.3. Risk management
6.2.4. Sentiment analysis
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by End-User
6.3.1. Institutional investors
6.3.2. Retail investors
6.3.3. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
7.1.1. Solution
7.1.2. Services
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Algorithmic trading
7.2.2. Portfolio management
7.2.3. Risk management
7.2.4. Sentiment analysis
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by End-User
7.3.1. Institutional investors
7.3.2. Retail investors
7.3.3. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
8.1.1. Solution
8.1.2. Services
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Algorithmic trading
8.2.2. Portfolio management
8.2.3. Risk management
8.2.4. Sentiment analysis
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by End-User
8.3.1. Institutional investors
8.3.2. Retail investors
8.3.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
9.1.1. Solution
9.1.2. Services
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Algorithmic trading
9.2.2. Portfolio management
9.2.3. Risk management
9.2.4. Sentiment analysis
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by End-User
9.3.1. Institutional investors
9.3.2. Retail investors
9.3.3. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Predictive Ai In Stock Market Is Segmented By Component
10.1.1. Solution
10.1.2. Services
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Algorithmic trading
10.2.2. Portfolio management
10.2.3. Risk management
10.2.4. Sentiment analysis
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by End-User
10.3.1. Institutional investors
10.3.2. Retail investors
10.3.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AlpacaDB Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Alphabet Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Alteryx Inc.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Amazon Web Services Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. C3.ai Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. DataRobot Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Fair Isaac Corp.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. H2O.ai Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. International Business Machines Corp.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Kavout
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Microsoft Corp.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. NVIDIA Corp.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Palantir Technologies Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. QuantConnect Corp.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Salesforce Inc.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. SAS Institute Inc.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Stock Rover
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Trade Ideas LLC
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Tradier Inc.
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. TrendSpider LLC
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Predictive AI In Stock Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Predictive AI In Stock Market Revenue (million), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 3: North America Predictive AI In Stock Market Revenue Share (%), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 4: North America Predictive AI In Stock Market Revenue (million), by Application 2026 & 2034
Figure 5: North America Predictive AI In Stock Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Predictive AI In Stock Market Revenue (million), by End-User 2026 & 2034
Figure 7: North America Predictive AI In Stock Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: North America Predictive AI In Stock Market Revenue (million), by Country 2026 & 2034
Figure 9: North America Predictive AI In Stock Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Predictive AI In Stock Market Revenue (million), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 11: South America Predictive AI In Stock Market Revenue Share (%), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 12: South America Predictive AI In Stock Market Revenue (million), by Application 2026 & 2034
Figure 13: South America Predictive AI In Stock Market Revenue Share (%), by Application 2026 & 2034
Figure 14: South America Predictive AI In Stock Market Revenue (million), by End-User 2026 & 2034
Figure 15: South America Predictive AI In Stock Market Revenue Share (%), by End-User 2026 & 2034
Figure 16: South America Predictive AI In Stock Market Revenue (million), by Country 2026 & 2034
Figure 17: South America Predictive AI In Stock Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Predictive AI In Stock Market Revenue (million), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 19: Europe Predictive AI In Stock Market Revenue Share (%), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 20: Europe Predictive AI In Stock Market Revenue (million), by Application 2026 & 2034
Figure 21: Europe Predictive AI In Stock Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Predictive AI In Stock Market Revenue (million), by End-User 2026 & 2034
Figure 23: Europe Predictive AI In Stock Market Revenue Share (%), by End-User 2026 & 2034
Figure 24: Europe Predictive AI In Stock Market Revenue (million), by Country 2026 & 2034
Figure 25: Europe Predictive AI In Stock Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Predictive AI In Stock Market Revenue (million), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 27: Middle East & Africa Predictive AI In Stock Market Revenue Share (%), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 28: Middle East & Africa Predictive AI In Stock Market Revenue (million), by Application 2026 & 2034
Figure 29: Middle East & Africa Predictive AI In Stock Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa Predictive AI In Stock Market Revenue (million), by End-User 2026 & 2034
Figure 31: Middle East & Africa Predictive AI In Stock Market Revenue Share (%), by End-User 2026 & 2034
Figure 32: Middle East & Africa Predictive AI In Stock Market Revenue (million), by Country 2026 & 2034
Figure 33: Middle East & Africa Predictive AI In Stock Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Predictive AI In Stock Market Revenue (million), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 35: Asia Pacific Predictive AI In Stock Market Revenue Share (%), by Predictive Ai In Stock Market Is Segmented By Component 2026 & 2034
Figure 36: Asia Pacific Predictive AI In Stock Market Revenue (million), by Application 2026 & 2034
Figure 37: Asia Pacific Predictive AI In Stock Market Revenue Share (%), by Application 2026 & 2034
Figure 38: Asia Pacific Predictive AI In Stock Market Revenue (million), by End-User 2026 & 2034
Figure 39: Asia Pacific Predictive AI In Stock Market Revenue Share (%), by End-User 2026 & 2034
Figure 40: Asia Pacific Predictive AI In Stock Market Revenue (million), by Country 2026 & 2034
Figure 41: Asia Pacific Predictive AI In Stock Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 2: Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 3: Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 4: Predictive AI In Stock Market Revenue million Forecast, by Region 2020 & 2034
Table 5: North America Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 6: North America Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 7: North America Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 8: North America Predictive AI In Stock Market Revenue million Forecast, by Country 2020 & 2034
Table 9: United States Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: Canada Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 11: Mexico Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 12: South America Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 13: South America Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 14: South America Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 15: South America Predictive AI In Stock Market Revenue million Forecast, by Country 2020 & 2034
Table 16: Brazil Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 17: Argentina Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 19: Europe Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 20: Europe Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 21: Europe Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 22: Europe Predictive AI In Stock Market Revenue million Forecast, by Country 2020 & 2034
Table 23: United Kingdom Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Germany Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: France Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Italy Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Spain Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Russia Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 29: Benelux Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 30: Nordics Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 33: Middle East & Africa Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 34: Middle East & Africa Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 35: Middle East & Africa Predictive AI In Stock Market Revenue million Forecast, by Country 2020 & 2034
Table 36: Turkey Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Israel Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 38: GCC Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 39: North Africa Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 40: South Africa Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Predictive AI In Stock Market Revenue million Forecast, by Predictive Ai In Stock Market Is Segmented By Component 2020 & 2034
Table 43: Asia Pacific Predictive AI In Stock Market Revenue million Forecast, by Application 2020 & 2034
Table 44: Asia Pacific Predictive AI In Stock Market Revenue million Forecast, by End-User 2020 & 2034
Table 45: Asia Pacific Predictive AI In Stock Market Revenue million Forecast, by Country 2020 & 2034
Table 46: China Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 47: India Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 48: Japan Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 49: South Korea Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 50: ASEAN Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 51: Oceania Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Predictive AI In Stock Market Revenue (million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How are large language models and reinforcement learning agents disrupting predictive analytics in stock markets?
Transformer-based language models now convert filings, earnings calls and news wires into structured features, cutting manual feature-engineering time by an estimated 40-60% versus 2021 workflows. Reinforcement learning agents are replacing static rule-based execution, with several systematic funds reporting 8-14 basis point improvements in implementation shortfall. Quantum-annealing portfolio optimizers remain pre-commercial, with no production deployment above USD 500 million in assets under management as of 2025.
2. Which companies lead the predictive AI stock market and how concentrated is the vendor base?
Infrastructure supply is concentrated: NVIDIA Corp., Microsoft Corp. and Amazon Web Services Inc. anchor the compute and orchestration layer, while SAS Institute Inc. and International Business Machines Corp. lead regulated model-risk tooling. Application-layer share is fragmented, with no single vendor exceeding an estimated 6% of the USD 295.7 million 2025 market. Alphabet Inc. and Palantir Technologies Inc. compete chiefly through cloud and deployment-framework distribution rather than financial-domain specialization.
3. What barriers to entry protect incumbents in this market?
Licensed market and alternative data is the steepest barrier, since exchange and vendor feed contracts carry annual escalators of 5-9% and multi-year minimum commitments. Regulatory moats matter too: model documentation and validation under EU AI Act high-risk classification and SEC examination regimes typically add 10-18% to implementation cost. Compute access is the weakest barrier, as cloud credits and hosted inference have reduced the cost of a proof-of-concept model to under USD 50,000.
4. What does the supply chain look like for predictive AI in stock markets?
The critical input is not a physical raw material but accelerator silicon and high-bandwidth memory, where NVIDIA Corp. and a small number of foundry suppliers control allocation. Secondary inputs are licensed datasets from exchange groups, card-panel aggregators and satellite imagery vendors, plus cloud-region capacity with sufficient low-latency interconnect to exchanges. Dependency risk concentrates in three nodes: advanced-node foundry capacity, memory supply, and the handful of firms licensed to redistribute consolidated tape data.
5. What notable partnerships and product launches have shaped the market since 2023?
In December 2022 Microsoft Corp. signed a 10-year data and analytics partnership with London Stock Exchange Group that included an approximate USD 2 billion investment. International Business Machines Corp. launched watsonx in May 2023 and Palantir Technologies Inc. released AIP in April 2023, both targeting governance-led enterprise deployments. NVIDIA Corp. introduced its Blackwell architecture in March 2024, raising throughput per rack for training and inference workloads.
6. Which end-user industries drive downstream demand and how do their buying patterns differ?
Institutional investors supply roughly 63% of spend, concentrated in an estimated 1,200-1,500 systematic funds that buy multi-year platform contracts with governance add-ons. The Retail Investors Market is the faster-expanding but lower-value pool, with average contract values 8-12x lower and materially higher churn. Exchanges and broker-dealers form a third demand pool, buying execution analytics and surveillance models tied directly to transaction revenue.
Methodology
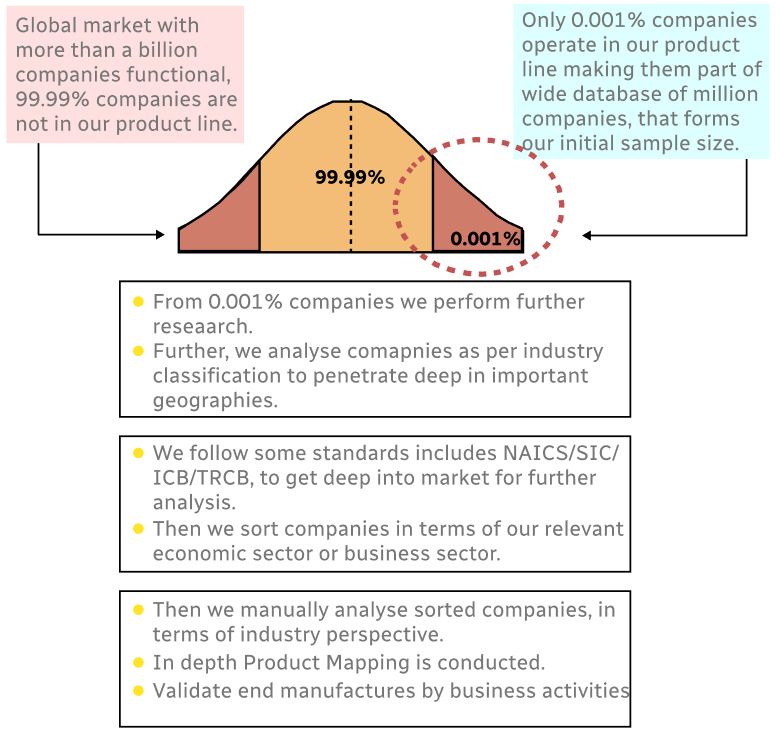
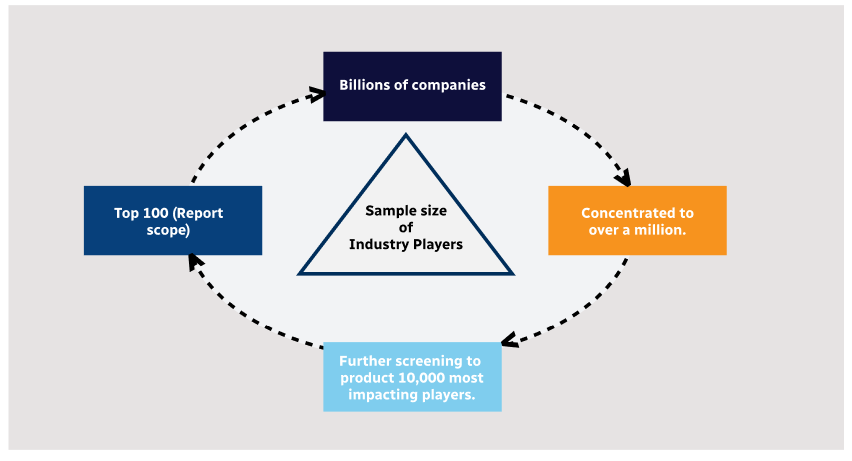
Step 1 - Identification of Relevant Sample Size from Population Database
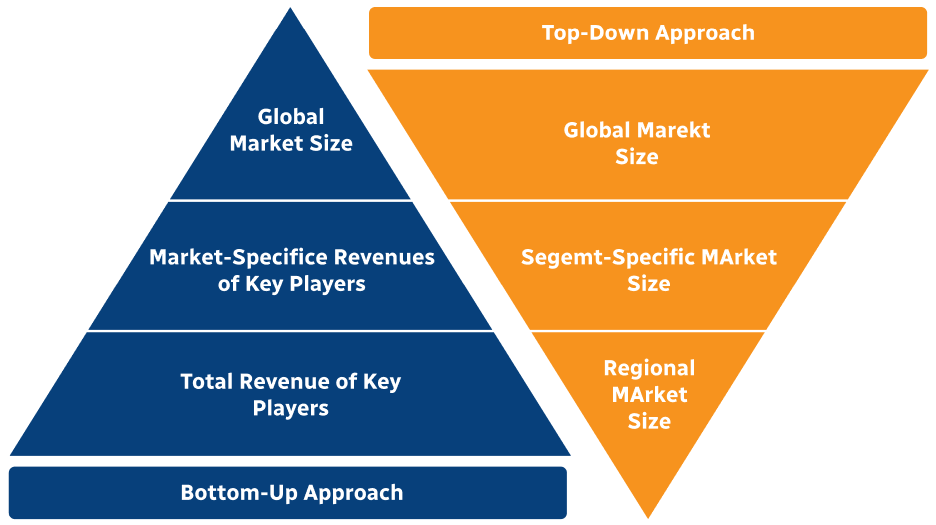
Step 2 - Approaches for Defining Global Market Size (Value, Volume & Price)
Top-down and bottom-up approaches are used to validate the global market size and estimate the market size for manufacturers, regional segments, product, and application. This cross-verification ensures accuracy across all market dimensions.
Note: *In applicable scenarios
Step 3 - Data Sources
Primary Research
Web Analytics
Survey Reports
Research Institute
Latest Research Reports
Opinion Leaders
Secondary Research
Annual Reports
White Paper
Latest Press Release
Industry Association
Paid Database
Investor Presentations
Step 4 - Data Triangulation
Involves using different sources of information in order to increase the validity of a study
These sources are likely to be stakeholders in a program - participants, other researchers, program staff, other community members, and so on.
Then we put all data in single framework & apply various statistical tools to find out the dynamic on the market.
During the analysis stage, feedback from the stakeholder groups would be compared to determine areas of agreement as well as areas of divergence
After gathering mixed and scattered data from a wide range of sources, data is correlated to come up with estimated figures which are further validated through primary mediums or industry experts and opinion leaders. This multi-source validation ensures high data integrity and reliability.